A mortgage decision can feel straightforward until you start comparing rates, affordability rules, deposit requirements and lender criteria. The mortgage adviser versus bank question is not simply about where you can get the lowest initial rate. It is about how much choice, guidance and support you need to reach a decision that suits your circumstances.
For some buyers and homeowners, approaching their own bank is a perfectly sensible starting point. For others, especially where income, credit history, property type or future plans need careful consideration, an adviser can save significant time and prevent an application being made to the wrong lender.
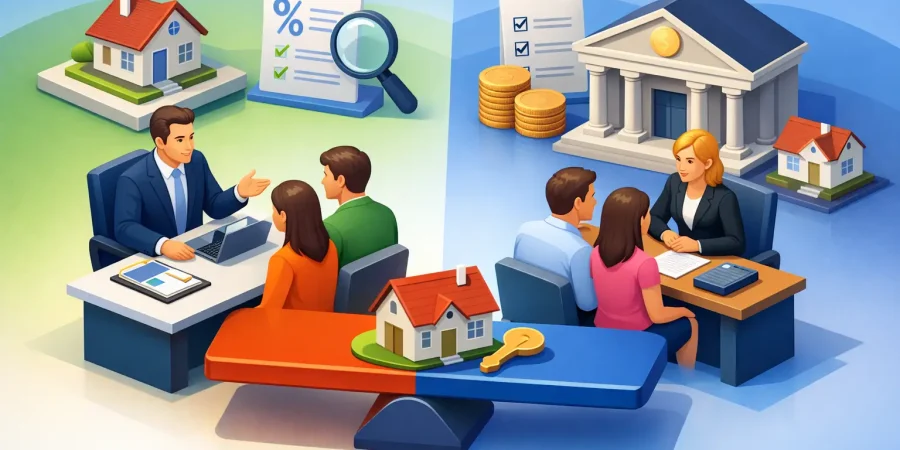
Mortgage adviser versus bank: the key difference
A bank can usually offer mortgages from its own range. Its staff can explain those products, assess whether you meet its lending criteria and process an application if you decide to proceed. This can be convenient if you already bank with them, have a simple application and are happy with the deal available.
A mortgage adviser looks at your wider situation before recommending a product. Depending on the adviser’s lender panel and the type of service offered, they may compare mortgages from a range of lenders rather than one bank alone. They then help match your requirements to lenders whose criteria are more likely to fit.
That distinction matters because mortgage rates only tell part of the story. A competitive rate is of little use if the lender will not accept your income structure, the property, your deposit source or the amount you need to borrow. The most suitable mortgage balances the rate, fees, term, flexibility and likelihood of a successful application.
When using your bank can make sense
Going directly to a bank may suit you if your finances are uncomplicated, you have already found a product you are comfortable with and the bank’s affordability assessment supports the borrowing you need. Existing customers may also find it convenient to keep their current account and mortgage arrangements in one place.
A direct application can feel quicker because there is one point of contact and fewer initial choices to make. If you are remortgaging with your existing lender, the process may also involve less paperwork in some cases, particularly where no additional borrowing or major changes are needed.
However, convenience should not replace comparison. Your bank does not normally tell you whether another lender could offer a lower overall cost, more flexible overpayments, a longer term or criteria that better reflect your circumstances. Before accepting a product, look beyond the monthly repayment and check the arrangement fee, valuation fee, early repayment charges and what happens when the introductory deal ends.
What a mortgage adviser adds
A good adviser starts with a conversation, not a product. They will ask about your income, outgoings, deposit, credit commitments, property plans and what matters most to you. For a first-time buyer, that may be understanding how much you can realistically borrow and what costs sit alongside the deposit. For a home mover, it may be coordinating a new mortgage with a sale. For an investor, it may be finding a lender whose buy-to-let criteria fit the property and rental income.
An adviser can also make complex situations easier to manage. Variable income, overtime, bonuses, self-employment, recent credit issues, existing loans or a desire to raise funds can all affect which lenders are appropriate. There is no single lender that is right for every applicant, so knowing where to apply can be as valuable as knowing what rate is available.
The application itself is another area where personal support can help. Mortgage lenders ask for detailed evidence, and a missing document or unclear explanation can slow progress. An adviser can tell you what is needed, help you present information clearly and stay in contact as the application moves through underwriting, valuation and offer.
At CoG Financial, this support can be delivered remotely, with documents supplied electronically and a named adviser available to explain the next step. That gives clients the convenience of a digital process without being left to interpret lender requests alone.
Choice does not always mean every lender
It is worth being precise about the word “choice”. Not every mortgage adviser works with the same lender panel, and not every lender is available through every intermediary. Some lenders only accept applications directly, while others work primarily through advisers.
Ask an adviser how they search the market and whether they charge a fee for their service. They should explain the scope of their service, any fees that apply and how they are paid. This gives you a clear picture of the options being considered before you act on a recommendation.
Equally, do not assume a direct bank deal is automatically cheaper because there is no adviser fee. A mortgage must be judged on its total cost and suitability, not one charge in isolation. An adviser’s fee, where one applies, may be worthwhile if it helps you avoid unsuitable applications, identify a better-fitting lender or make a complicated transaction less stressful. In other circumstances, a straightforward direct deal may be the right choice.
Advice, execution-only and responsibility
There is an important difference between receiving mortgage advice and choosing an execution-only application. With advised mortgage services, the adviser assesses your needs and makes a recommendation. The recommendation should be suitable for your circumstances and supported by an explanation of why it has been made.
An execution-only route means you select the mortgage yourself without receiving a personal recommendation. Some borrowers are confident doing this, particularly if they understand mortgage products and have simple circumstances. But it places more responsibility on you to assess whether the product, lender criteria and features are right.
A bank appointment may be advised or non-advised depending on the service and product, so it is sensible to ask. Do not be afraid to request a plain-English explanation of the recommendation, the costs involved and the risks of fixing for a particular period.
Compare more than the headline rate
A two-year fixed rate that looks attractive may not be the best option if you expect to move soon, want to make large overpayments or may need to change your mortgage term. Likewise, a five-year fixed rate can provide valuable certainty for household budgeting, but early repayment charges could restrict your options if your plans change.
Consider the overall mortgage package. Look at the interest rate and monthly payment, but also the product fee, incentives, loan term, overpayment allowance, portability and the standard variable rate after the deal finishes. If you are consolidating debts or raising funds against your home, consider the total amount repaid over the full term. Reducing a monthly payment by spreading borrowing over a longer period can increase the overall cost.
Protection deserves a place in the conversation too. A mortgage is a long-term commitment, and illness, death or loss of income can quickly change a household’s finances. Life insurance, critical illness cover and income protection are separate decisions, but reviewing them alongside a mortgage can help ensure your repayments and family have appropriate support.
Questions to ask before you choose
Whether you speak to a bank or an adviser, use the first conversation to test the service as well as the mortgage. Ask what lenders or products are being considered, how your income has been assessed, what fees and charges apply, and what could cause an application to be declined or delayed.
You should also ask who will keep you updated once the application is submitted. A mortgage offer is only one stage of the process. Clear communication with your adviser, lender, solicitor and estate agent can make a real difference when deadlines are tight.
For many people, the choice comes down to certainty and support. If your bank has a product that genuinely suits your needs and you are comfortable handling the process directly, that route may work well. If you want broader comparison, help with lender criteria and a person who will stay alongside you from eligibility to completion, speaking to a mortgage adviser is a practical next step.
Before making an offer, switching deal or applying for additional borrowing, take the time to check your eligibility and talk through the details with someone who will listen. A mortgage should fit not only the property you want now, but the life you expect to lead while you are paying for it.